10 Bullet Journal Ideas for Budgeting That Actually Work
Money comes in, money goes out, and by the end of the month you have no idea where it went.
You check your balance, you feel a knot in your stomach, and you promise yourself that next month will be different. I used to feel the same way, and the fix was not a new app or a strict plan that lasted three days.
By the end of this post, you will know how to set up ten simple bullet journal pages for budgeting, and you will have a clear first page to start tonight. You do not need fancy pens, and you do not need perfect handwriting. You need a notebook, a pen, and ten minutes.
The bullet journal method was created by Ryder Carroll, and his book, The Bullet Journal Method, came out in 2018. His idea was simple. Put your plans, your lists, and your notes in one place, in a way that fits your real life.
That is why it works so well for money. You see the numbers, you write them by hand, and your brain slows down enough to notice what is really going on.
Your Simple Budgeting System in Five Small Daily Habits
Five pages do most of the work. Start with these, then add the rest when you are ready.
Ten minutes a day is enough to stay on track.
1. Start With a Monthly Budget Log That Makes Budgeting Feel Simple and Clear
Ever opened your banking app and thought, where did it all go?
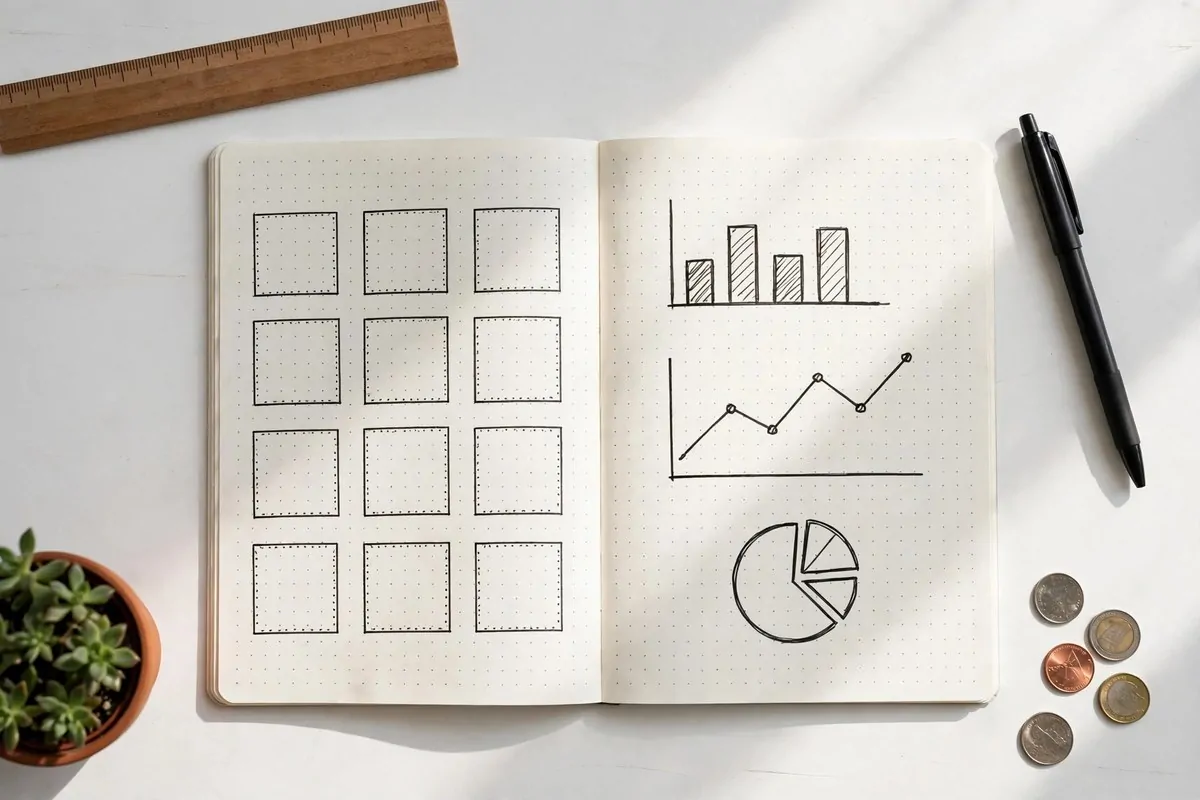
A monthly budget log answers that question on one page, in your own handwriting. It is a plain list of money in, money out, and money left.
It helps you because you stop guessing. When the numbers sit in front of you, you can see the gap between what you planned and what you spent. That gap is where your next choice lives.
Try it today in three steps. First, draw two columns on a fresh page and label them money in and money out.
Next, write your pay at the top and your regular costs below it, like rent, food, transport, and phone. Then add the two columns and write the amount left at the bottom in a box.
Watch out for the trap of making it too neat.
If you spend an hour drawing lines and borders, you will not want to open the page again. Keep it rough, keep it real, and let it look like a working page.
A good first result looks like this. You finish the page in under fifteen minutes, and you can point to one cost that surprised you. That one surprise is your first win, because now you can do something about it.
2. Use a Daily Spending Tracker That Catches Small Leaks Before They Add Up
What if the problem is not one big cost, but ten small ones you forgot by dinner time? A spending tracker is a simple daily list, with the date, what you bought, and the amount. Nothing more.
Why does writing it down help you so much? Because small amounts feel harmless on their own.
A snack here, a drink there, a quick top up for the car. On paper, side by side, they tell a very different story.
Do it tonight in two steps. First, make a small table with three columns: date, item, and amount.
Then, each night before bed, spend two minutes filling in that day. If you miss a day, just pick it up the next morning and keep going.
| Date | Item | Amount |
|---|---|---|
| Monday | Groceries | Write the total here |
| Tuesday | Bus fare | Write the total here |
| Wednesday | Lunch out | Write the total here |
Watch out for shame. This page is not there to scold you. It is there to show you facts, so you can choose one small change next week instead of trying to change everything at once.
After one week, a good result is a full page with no blank days and one clear pattern. Maybe lunch out costs more than you thought.
Maybe weekends cost twice as much as weekdays. Now you know, and knowing is the whole point.
3. Keep a Bill Tracker That Puts Every Due Date in One Safe Place
Picture this. A bill slips your mind, a late fee shows up, and money you could have saved just vanishes. A bill tracker stops that from happening, and it takes five minutes to set up.
It is a list of every regular bill, the amount, and the date it is due. Rent, power, water, phone, and any other regular cost all live on the same page. You check it at the start of the month, and you check it again each week.
Set it up today in three steps. First, list every bill you pay each month.
Next, write the due date and the usual amount beside each one. Then tick each bill off the day you pay it, and write the real amount if it changed.
What should you watch out for? Bills that change each month, like power and water, can catch you out. Leave space beside the usual amount so you can write the new amount each time, and keep a small buffer in your plan for a higher month.
A good first result is simple. At the end of the month, every bill has a tick beside it, and no late fee showed up. That quiet month is a win, even if no one else sees it.
4. Build a Savings Tracker That Turns Small Weekly Amounts Into Real Money
Want to save, but the goal feels too far away to start?
A savings tracker breaks it into small steps you can see. You draw a row of boxes, and you colour one in each time you save.
It helps you because progress you can see feels real. A big goal on its own can feel cold and far away. A row of boxes that slowly fills up gives your brain proof that you are moving.
Here is how the 52 week challenge works, and why so many people love it. You save one dollar in week one, two dollars in week two, three in week three, and you keep adding one dollar each week until week 52.
Add it all up, and the total is $1,378.
That is what small weekly steps can do when you stick with them.
Try it today in three steps. First, pick a goal and write it at the top, like a safety cushion or a new laptop.
Next, draw your boxes and label them with the weekly amounts. Then save the first amount this week, colour the first box, and write the date beside it.
I started with five dollars a week, because that felt easy enough to keep doing. Watch out for picking an amount that is too high in week one, because you will quit by week three. Start low, stay steady, and raise it later if you want to.
A good first result after a month is four coloured boxes and money set aside that you did not touch. That is not small. That is a habit, and habits beat big promises every time.
5. Plan Your Week With a Meal Page That Cuts Food Waste and Saves Cash
How many times have you bought food, then thrown half of it away?
A meal plan page fixes that with one short list each week. You plan five or six meals, you shop once, and you use what you buy.
It helps you because food is one of the few costs you can change fast. You cannot change rent this week, but you can change what you cook, how much you buy, and how often you eat out. That is real power over your month.
Do it today in two steps. First, look in your cupboards and fridge and write down what you already have. Next, plan meals around those foods, then write a short shopping list for the missing items only.
- Pick meals you already know how to cook well.
- Plan one leftover night each week to use up cooked food.
- Keep the shopping list short and stick to it in the shop.
- Write the plan where you will see it, like on the fridge door.
Watch out for planning meals that need ten new items each time. That kind of plan costs more, takes longer, and falls apart by Wednesday. Simple meals, repeated often, save the most money.
A good first result is a week with less food thrown away and one less trip to the shops.
If you saved even a little, write the amount at the bottom of the page. Seeing it in numbers makes you want to do it again next week.
6. Try a No Spend Day Tracker That Makes Saving Feel Like a Fun Challenge
Could you go one day without spending a single dollar? A no spend day tracker turns that question into a small challenge. You pick certain days, you spend nothing on those days, and you mark each win with a tick or a star.
It helps you because it breaks the habit of spending without thinking. Most days, money leaves your pocket because of routine, not need. A no spend day forces a pause, and that pause shows you how much of your spending is just habit.
Start today in three steps. First, pick two days this week and circle them on your calendar.
Next, plan those days in advance, so you have food at home and a free plan for the evening. Then, at the end of each day, mark it as a win if you spent nothing.
Watch out for making the rules too hard. A no spend day still allows a real need, like medicine or an urgent trip. The point is to cut the extra spending, not to punish yourself for living your life.
Here is a fact worth knowing. In the Federal Reserve SHED survey for 2024, 63% of adults said they could cover a 400 dollar surprise cost with cash or its equivalent. That number shows why a small cushion matters so much.
What it means for you is simple. Every no spend day adds a little to that cushion, and a cushion turns a surprise into a small problem instead of a crisis.
A good first result is two marked days in your first week and a note about what you did instead of spending.
Maybe you cooked at home, or you walked instead of taking a taxi. Those notes matter, because they show you a life you can enjoy without spending more.
7. Make a Payday Plan Page That Gives Every Dollar a Job Before You Spend It
Payday feels great for about two days, and then the money starts to slip away. A payday plan page stops that slide. On the day your pay arrives, you sit down for ten minutes and you give every dollar a job.
Why does this help you? Because money with no plan gets spent on the loudest thing in front of you.
Money with a plan goes where you told it to go. That one shift changes the whole month.
Do it on your next payday in three steps. First, write your pay at the top of the page.
Next, split it into groups: bills, food, transport, saving, and fun money. Then write the amount for each group, and move the saving amount aside on the same day, before you spend anything else.
| Group | Amount | Done |
|---|---|---|
| Bills | Write it here | Tick when paid |
| Food | Write it here | Tick when planned |
| Saving | Write it here | Tick when moved aside |
| Fun money | Write it here | Tick when set |
Watch out for leaving out fun money. If your plan has no room for joy, you will break it by week two. A small amount for fun, planned in advance, keeps the rest of the plan alive.
A good first result is a page where the groups add up to your pay, with nothing left unplanned. You will feel calmer the next morning, because you already know where the money is going.
8. Keep a Wish List Page That Stops Impulse Buys Without Saying No Forever
Seen something you want, right now, and your hand is already reaching for your wallet?
A wish list page gives that feeling a safe place to wait. You write the item down, you wait, and you decide later with a clear head.
It helps you because most wants fade fast. What feels urgent today often feels unimportant in two weeks. A wish list lets you keep the joy of wanting something, without paying for it before you know if you really want it.
Try it today in two steps. First, make a page with four columns: item, amount, date added, and still want it. Next, when you want to buy something that is not a need, write it on the list instead of buying it, and set a wait time of 30 days.
Watch out for the trap of adding everything and never checking the list again. Set a date each month to look at it. Cross off the items you no longer want, and keep the ones that still matter to you after the wait.
A good first result is a list with five items on it and zero bought on impulse that week. After 30 days, if you still want one item and you have room in your plan, buy it with a clear mind.
That is not a failure. That is the system working.
9. Link Daily Habits to Money With a Habit Tracker That Builds Slow Steady Progress
Money habits are really just daily habits with a price tag. A habit tracker is a grid with days across the top and habits down the side. You tick a box each day you do the habit, and the row of ticks grows.
It helps you because money goals feel big and far away, but daily habits feel small and doable. Cook at home four nights a week. Pack lunch three days a week.
Check your balance each morning. Each tick is a small win, and small wins stack up.
Set it up today in three steps. First, pick three habits only, and write them down the side of the page.
Next, draw a box for each day of the month beside each habit. Then tick each box on the day you do the habit, and leave it blank if you miss a day, with no guilt and no fuss.
I keep mine to three habits, because five felt like a chore and I stopped opening the page. Watch out for that same trap. Three habits done well beat ten habits that last four days.
- Cook at home instead of buying lunch out.
- Move a small amount to saving on payday.
- Check your spending tracker for two minutes each night.
- Drink water at home instead of buying a drink out.
A good first result is a page with more ticks than blanks after two weeks, and one habit that now feels automatic. That habit is now saving you money without you having to think about it, and that is the goal.
10. End the Month With a Review Page That Shows What Worked and What to Change
What if the end of the month felt like a win, instead of a worry? A monthly review page makes that happen. You sit down for twenty minutes, you look at your pages, and you write down what worked, what did not, and what you will change next month.
It helps you because a plan you never check is just a wish. A review turns your notes into lessons, and lessons turn into a better plan next month. Without it, you repeat the same month again and again.
Do your first review in three steps. First, add up your spending tracker and compare it with your monthly budget log.
Next, write three things that worked well and one thing to change. Then write your plan for next month in two short lines, and start the new pages.
Here is a fact that puts your biggest cost in clear view. The Bureau of Labor Statistics Consumer Expenditure Survey for 2024 found that the average household spent $26,266 a year on housing.
That is the largest cost for most homes. What it means for you is that housing deserves the most care in your plan, but the small daily costs are where you can act fastest.
Watch out for turning the review into a blame session. You are not there to punish yourself for a bad week. You are there to find one change that will make next month easier, and then to make that change.
One more fact can help you stay calm about surprises.
In the Bankrate 2025 Emergency Savings Report, 41% of adults said they would pay a 1,000 dollar surprise cost from savings.
That shows a cushion is possible for many people, and it grows one small step at a time. What it means for you is that your savings tracker and your review page are working together, month by month, to build that cushion.
A good first result is a review page with three wins written down and one clear change for next month. If you can name the wins, you will want to do it again. That is how budgeting becomes a habit, not a chore.
Key Takeaways for Budgeting You Can Use Starting Today
- Start with a monthly log so you can see money in, money out, and money left on one page.
- Write down daily spending each night, because small amounts add up faster than you think.
- List every bill with its due date, then tick it off the day you pay it.
- Colour in one savings box each week and watch a small habit turn into real money.
- Plan meals from food you already have, then shop with a short list for the missing items only.
- Pick two no spend days each week and mark each win so you can see your progress.
- Split your pay into groups on payday, move saving aside first, and keep a little fun money in the plan.
- Write wants on a wish list, wait 30 days, and buy only the ones that still matter.
- Track three daily habits with ticks, because small daily wins stack into real change.
- Review your pages at month end, keep three wins, and pick one change for next month.
What to Do First Today in Three Short Steps
First, grab a notebook and a pen, open a fresh page, and write your monthly budget log. Pay at the top, regular costs below, and the amount left in a box at the bottom.
Second, start your spending tracker on the next page, with three columns for date, item, and amount. Fill in today before bed, even if it is only one line.
Third, pick your first savings amount, even if it is small, and write it on a new savings tracker page. Colour the first box when you set it aside.
That is it. Three pages, ten minutes, and a clear start. Open your notebook tonight, and let tomorrow be the first day you know exactly where your money is going.