7 Simple Ways to Use the 50-30-20 Budget Rule for Beginners
You open your bank app on Sunday morning, and your stomach drops a little. The pay came in days ago, yet the balance already looks thin, and you can’t say where it went.
That lost feeling is the exact problem this plan fixes. After you read this, you will know how to split what comes in into three clear parts, and you will know what to do with each part today. You will not need a long sheet, and you will not need a perfect month to start.
The 50-30-20 budget gives you that split, and it takes less than one hour to set up.
Keep this page open while you work through it. By the end, you will have three numbers for your own month, and a first move you can make before bed tonight.
See Your Whole Month in Three Parts Before You Spend a Single Coin
1. Split Your Pay Into Three Clear Parts, So You Know Where Every Part Goes
Have you ever tried a plan that felt like homework, with ten boxes and twenty rules? This one is not like that, because it asks you to sort all your spending into only three groups.
The idea comes from a real book, not a random post online. Elizabeth Warren and Amelia Warren Tyagi shared it in their 2005 book All Your Worth, and they called it the Balanced Money Formula. They built it for busy people who wanted a clear rule, not a thick guide.
For you, that history means this plan has been tested by real readers for years, not just tried for a week. Your job today is to trust the three groups, and let the simple split do the hard work for you.
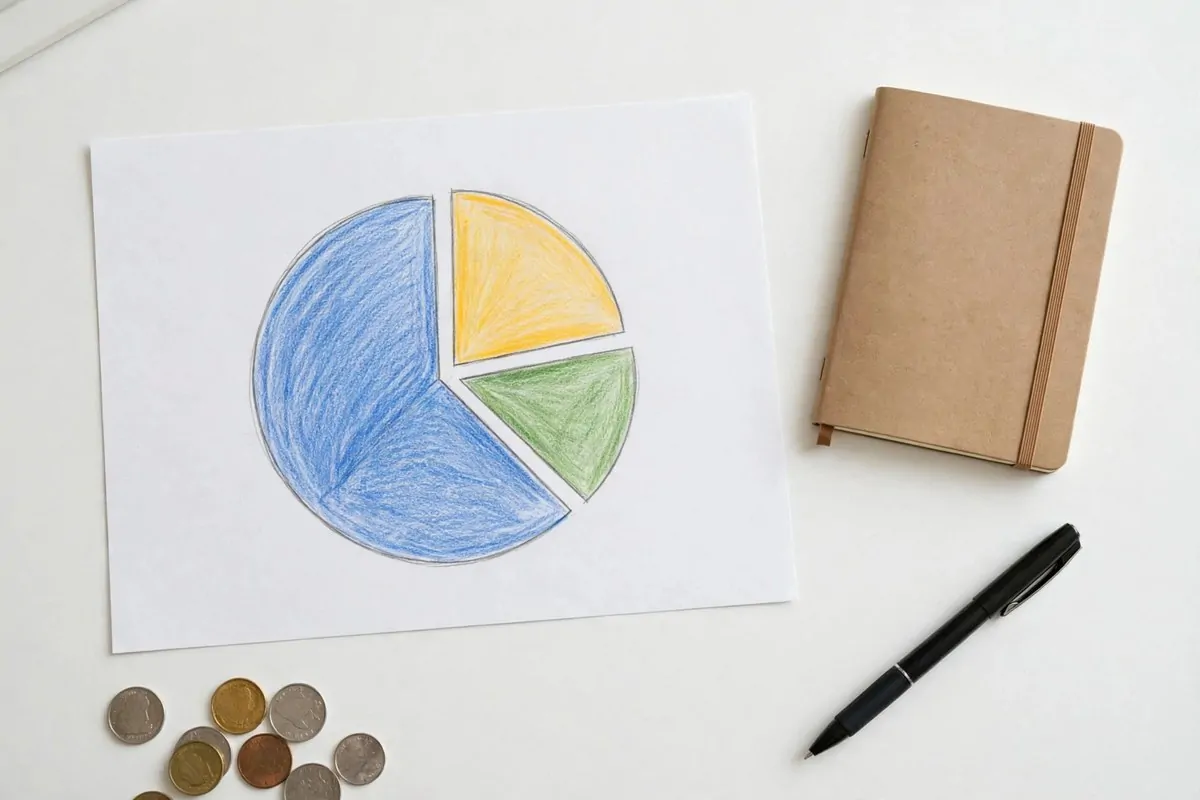
Half goes to needs, three parts out of ten go to wants, and two parts out of ten go to savings and future plans. You start from what actually lands in your account after tax, not the pay figure on paper. That one choice keeps every number honest, because you can only spend what you truly have.
Try this first: write 50, 30, and 20 on a scrap of paper, and keep it where you can see it while you read the next steps.
Watch out for one trap here. If you start from your pay before tax, every group will look bigger than it is, and the plan will fall apart by week two.
A good first result looks like this. You can say your three groups out loud, and you know which number you start from. If you can do that, you are ready for the next step.
2. List Your Needs First on Sunday Night, Before You Spend on Anything Else
Sunday night, you sit with a cup of tea and a blank page. You write down the bills that keep your home and your work life running, and you don’t guess at them.
Rent is a need, food for the home is a need, and power, water, and gas are needs too. Travel to work is a need, and basic clothes, soap, and other home basics are needs as well. If you would still have to pay it if work stopped for a week, it is a need, so put it on this list.
You are not alone if this list looks big. A 2024 survey from the United States Bureau of Labor Statistics found that housing was the largest cost for the average home, at 26,266 dollars for the year. That fact tells you why your home cost takes so much room, and it is not a sign that you have failed.
For you, this means you should look at your home cost first, before you cut small joys. Your move today is to write the home cost down, then add the other needs, and see the real total in one place.
Now add up the list, and check it against half of what comes in. If the total is near half, your plan fits, and if it is over half, you will bend it later in step 6, so don’t panic now.
I keep my own needs list on one page, and it takes me five minutes to check it. A good first result is a short list you trust, with no surprise bill hiding off the page.
3. Keep the Fun You Truly Miss, With a Set Limit So You Enjoy It Calmly
Think back to last month for a moment. Did you cut out every fun thing, then feel tired and give up on the whole plan by week three?
Wants are the things that make life sweet, and they are not bad. Eating out is a want, a film night is a want, and gifts for friends and a trip for fun are wants too. This plan gives them a clear place, so you can enjoy them without guilt.
When you set money aside for wants, you stop the all or nothing trap. You know the needs are paid, and you know the future has its share too, so fun feels calm, not risky.
Pick two or three wants that bring you real joy, and write them down. Give them a clear limit for the month, and put that limit where you will see it. If you love to eat out, keep that, and let the rest wait for another month.
Watch out for small buys that hide in this group, because ten small buys can eat the whole 30 share. A good first result is one fun thing you enjoy this week, with money still left in the wants pot after it.
4. Move Your Savings Aside First, Before Fun Gets a Chance to Take That Money
Try this first on the day money comes in. Move the savings share aside at once, before you spend on anything fun, because later in the month there is often little left.
Savings are money you set aside for later, and future plans are the big goals you want to reach in time. The 20 part can be money for a rainy day, money for a big goal, or money you put away for a calm future. You can shape this part around your own goals, and it still counts as long as the money is set aside.
This small move matters more than it looks. A 2024 report from the Federal Reserve, based on its Survey of Household Economics and Decisionmaking, found that 63 percent of adults said they would cover a 400 dollar surprise cost with cash or its equivalent. That means more than one in three adults could not do that, and a small safety pot is what puts you on the safe side.
For you, this means your first savings goal is simple, and it is not a huge pile of money. Your move today is to set aside enough to cover one small surprise, then build it up month by month.
Bankrate found in its 2025 report that only 41 percent of adults in the United States said they would pay for a 1,000 dollar surprise cost from savings.
For you, this means a 1,000 dollar surprise is the next goal after your first small pot, and your 20 share can build toward it bit by bit.
Keep it in a separate place, so you don’t mix it with daily spending. When it is out of sight, it is easier to leave it where it is, and it can grow without a daily fight.
A good first result is a small pot that stays untouched for a full month.
5. Start This Week With Three Small Steps, Not Next Month When You Feel Ready
You don’t need to wait for a new month or a perfect day. You can start this week, and the start can be small.
First, write down what comes in this month, and use the lowest amount you expect if your pay changes. Next, split that total into the three parts, with 50 for needs, 30 for wants, and 20 for savings and future plans. Then move the savings part aside first, and put it where you will not spend it by mistake.
If you get paid each week, add the weeks up and use that total as your base. A plain sheet of paper works just as well as any fancy tool, so you don’t need to buy a thing.
SoFi describes the 52-week challenge as saving 1 dollar in week one, adding 1 dollar each week up to 52 dollars in week 52, for a total of 1,378 dollars in one year.
For you, this means you can start your 20 share with just 1 dollar this week, and the small weekly rise does the hard work for you.
I check my plan on the same day each week, and that small habit keeps me on track. Watch out for the urge to make the plan perfect, because a plain plan you keep beats a perfect plan you drop.
A good first result looks like this. You have three numbers on one page, the savings share is already aside, and the big needs are paid. If you can say yes to those three things, your first week is a win.
6. Bend the Split When Needs Take More Than Half, Because a Plan You Keep Wins
Does half feel too small for your needs, with rent and food taking most of what comes in? You are not alone, and you don’t have to force a split that does not fit your life.
For many people, needs take more than half of what comes in, and that is very common in a high-cost month. Rent can be high, food costs can rise, and travel can take a big share. If that is your case, don’t feel bad, because the rule can still help if you bend it a little.
A 60-25-15 split is still a plan, and it is far better than no plan at all. The goal is to move toward the 50-30-20 split over time, not to force it in one month.
Start by finding the biggest need that you can change, because for most homes, that is rent, food, or travel. Can you plan meals for the week and buy food in larger packs? Can you walk for short trips instead of paying for travel each time?
You don’t need to change all three at once, so pick the one with the biggest saving and work on that first. A good first result is one small change that moves your needs share down by a little, and you can see it in next month’s numbers.
7. Skip These Three Mistakes, or Your Plan Will Slip Apart in Week Two
You have a plan now, so let us protect it. These three slips catch most people, and each one is easy to spot once you know it.
The first mistake is to make the plan too hard. A plan with ten groups and twenty rules is hard to keep, and most people drop it in the first week. Three groups are enough, and simple wins because simple fits a busy life.
The next mistake is to forget small spends, because a small buy here and there can look tiny. Ten small buys can take a big share, and they often sit in the wants group without you noticing.
Write them down for one month, even if it feels boring, and you will see the pattern fast. Another mistake is to set savings last, because when savings come last, there is often nothing left. Move savings first, even if the amount is small, because a small save on day one beats a big plan to save on day thirty that never happens.
I use Sunday evening for my five minute check, because the week feels calm then. Pick one day, give the plan five minutes, and keep the plan where you can see it, on the fridge, in your notebook, or as a note on your phone.
A good first result is a plan you still use in week four, not a plan you forgot in week two.
7 Simple 50-30-20 Budget Takeaways to Help You Split Your Money With Calm
- Learn the split from the book, because a clear three-way split shows you where each part goes before you spend.
- List your needs on one page first, because home and food take the biggest share, and a full list stops surprise bills.
- Give fun a set limit, because a limit lets you enjoy two or three joys without guilt.
- Move savings aside on the first day, because the Federal Reserve report shows many adults have no small safety pot, and an early move puts you on the safe side.
- Start this week with three small steps, because a small start beats a perfect plan that never leaves the page.
- Bend the split to 60-25-15 when life is tight, because a plan you keep is worth far more than a perfect split you drop.
- Check the plan for five minutes each week, because a short weekly look catches small slips early, before they grow.
Do These Three Short Steps Today, and Let Your Month Feel Lighter This Week
You now know the split, and you know what to do with it. Half for needs, three parts out of ten for wants, and two parts out of ten for savings and future plans.
Do this first today, in three short steps. Step one, write down what comes in this month. Step two, work out your three numbers, and move the savings share aside first.
Step three, pay the big needs, and put the plan where you can see it. Then live your month with a clear head, and check the plan for five minutes each week.
Each week, ask if you paid your needs, stayed close to your wants limit, and moved your savings aside.
If the answer is yes to two out of three, you are doing well. Over time, those small steps will build a calm habit that makes the next month feel lighter than the last.